
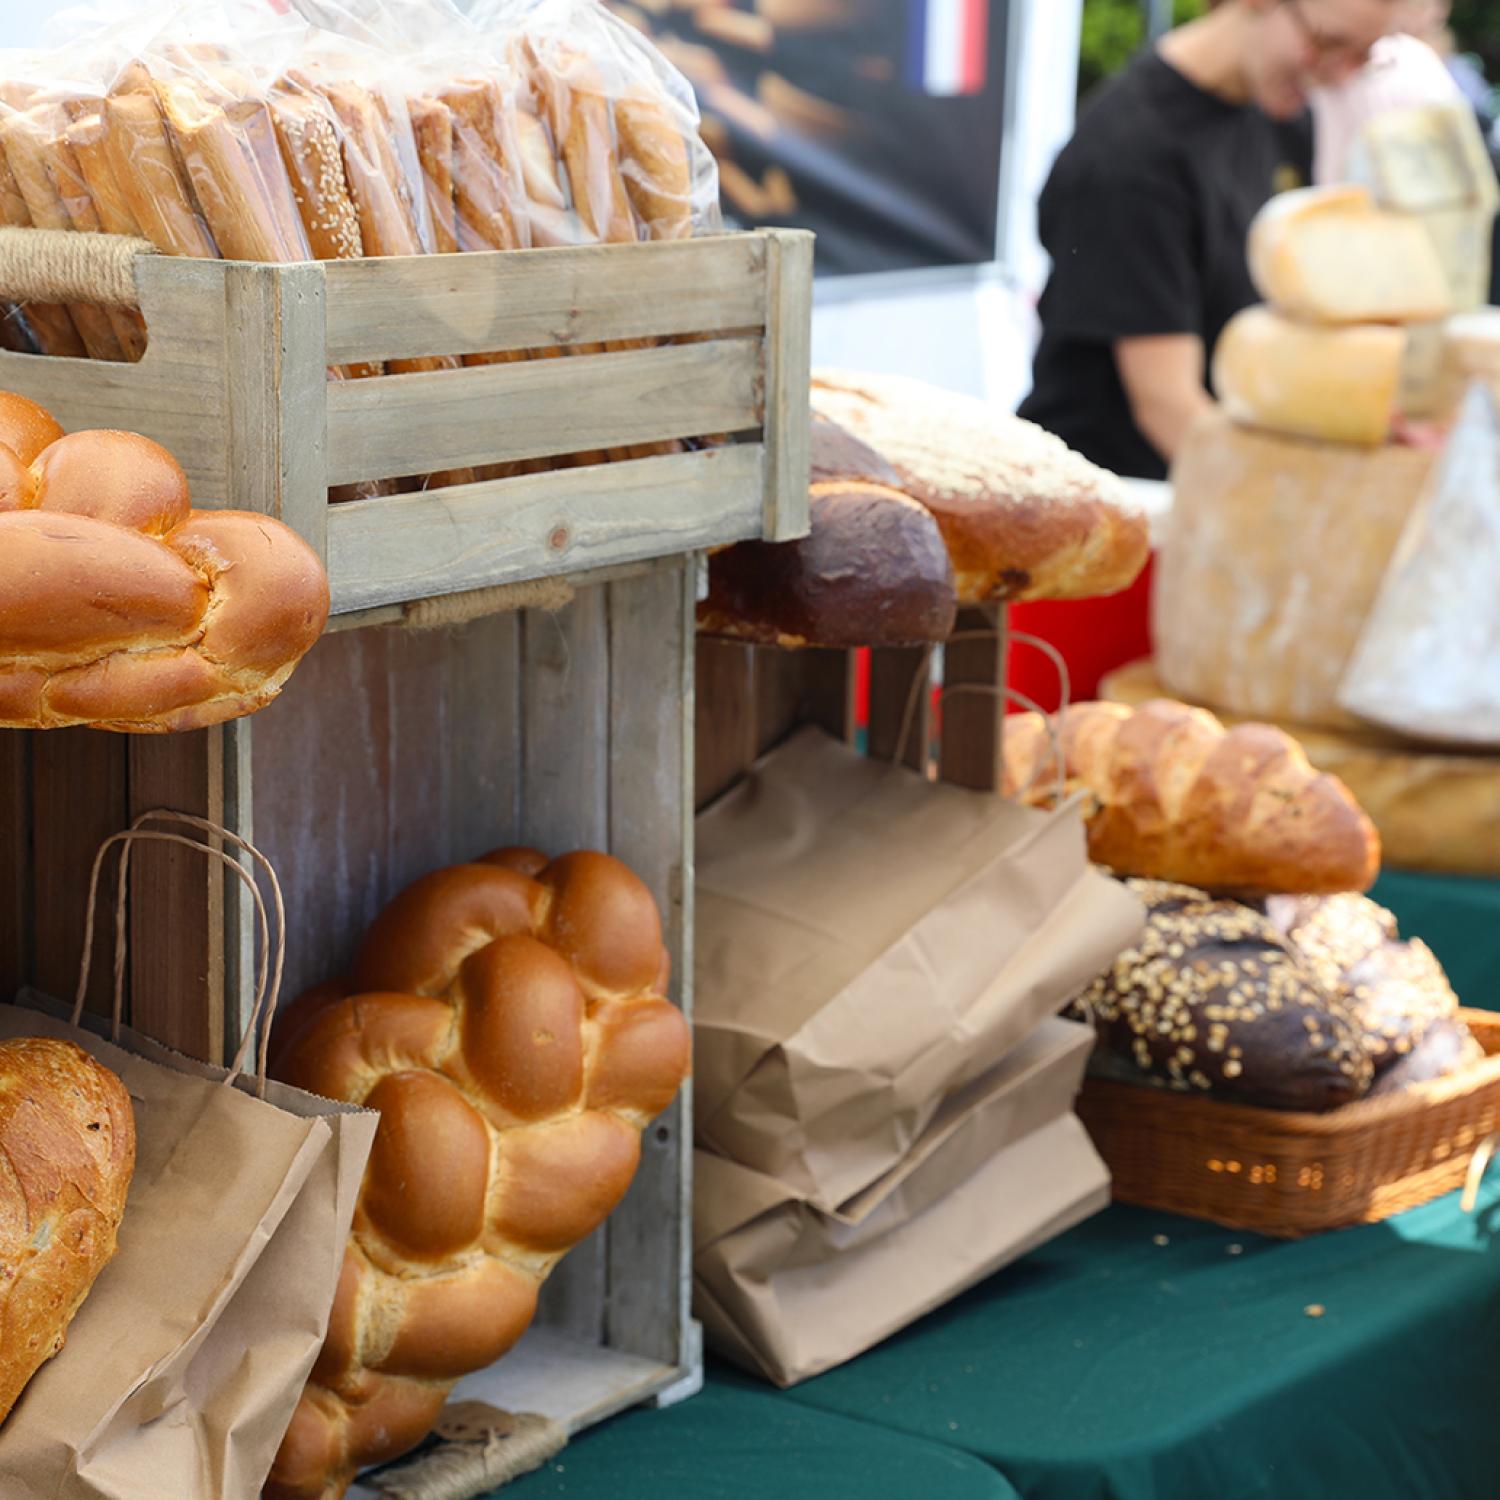


Why do food market stalls need insurance?
Food traders work in fast-paced, public-facing environments where accidents, injuries, and equipment problems are an everyday possibility. Insurance can help you manage the financial impact on your business.
A customer falls ill
Food poisoning or an undisclosed allergen can leave customers seriously unwell. Even if you followed every food hygiene rule, you may still face a claim if a customer believes your food made them ill.
Public and products liability insurance can help with legal defence costs and any compensation owed if a customer brings a claim against you. Defending a case, even an unfounded one, can be costly, so having the right cover in place can help protect you.
An employee injury
Working at a food stall can be physical. Staff often lift heavy equipment, work around open flames and hot surfaces, and set up in different weather conditions. A colleague could burn themselves on cooking equipment, trip while carrying stock, or injure their back moving a generator.
Employers’ liability insurance can help cover the legal defence costs and compensation for a work-related injury or illness claim made by an employee. For most businesses with staff, it’s also a legal requirement in the UK.
Your equipment gets damaged
A market stall depends on its kit. If expensive items like gazebos, cooking equipment, generators, or display units are damaged or stolen, you may not be able to trade.
Business contents insurance can help cover the cost of repairing or replacing equipment and stock if it’s damaged, destroyed, or stolen, to help you get back to trading.
What insurance is available for food market stalls?
Public and products liability insurance
Public and products liability insurance can help protect your food stall if a customer or member of the public is injured or their property is damaged as a result of your work. It also typically includes products liability cover, which can help if someone claims they were harmed by food you sold or prepared.
This cover can help with compensation and legal defence costs, whether an incident happens at your pitch, at a customer’s home, or at an event. Many market operators and councils will also require proof of public and products liability insurance before letting you trade. Cover is available up to £10 million.
Employers’ liability insurance
If you have any members of staff, including part-time or casual helpers, employers’ liability insurance is a legal requirement for UK businesses (external link). It can help with the costs of defending or settling a claim if an employee suffers a work-related injury or illness.
At Hiscox, employers’ liability cover is available alongside public and products liability insurance – so you can build both into a single policy.
Business contents insurance
Business contents insurance can help protect the equipment and stock that you keep at a fixed premises and that your stall depends on. Whether your cooking kit is damaged, your gazebo is stolen overnight, or a fire destroys your kitchen, this cover can help with the cost of repairs or replacements.
You can also add portable equipment cover to protect items you regularly take away from a fixed base, for example, to different markets or event locations. This cover can even be extended to locations outside the UK if you attend events overseas.
Tell us more about your food market business and we’ll help to build your tailored insurance policy.
Build my coverInsurance for food market stalls: FAQs
Am I covered if I trade at multiple markets or events?
Yes. Hiscox public and products liability insurance can cover your business activities whether you trade from a regular pitch or travel to different markets, events, and festivals throughout the year. Our standard cover extends to claims from activities carried out anywhere in the UK or Europe, so you’re covered whether you operate your stall in Plymouth or Paris. When setting up your policy, let us know how and where you trade so we can help arrange cover that reflects your needs.
Does public and products liability insurance cover food poisoning?
Public and products liability insurance typically includes products liability cover, which can help if a customer claims they became ill due to food you prepared or sold. This can apply even if you believe the claim is unfounded – the costs of defending a case can add up quickly, and having cover in place can help manage that financial impact. Cover is subject to the terms of your policy.
Am I covered for theft or damage when transporting my stall equipment?
Business contents insurance is usually designed to cover equipment at a fixed premises. Items that are regularly used away from a fixed base may require portable equipment cover. This can cover accidental loss, damage, or theft while you’re on the move between locations.
Am I covered for selling alcohol at my stall?
Selling alcohol can affect the type and level of cover your business needs. If you sell alcohol as part of your offering, it’s important to disclose this when setting up your policy so we can help make sure you have the right protection in place.
Does business insurance cover damage to rented market space or equipment?
Accidental damage to a rented pitch, stall structure, or hired equipment may be covered under your public and products liability insurance, depending on the terms of your policy. If you regularly hire equipment or rent space from market operators, it’s worth discussing this when arranging cover to ensure suitable protection is in place.
Related articles and guides
The importance of customer experience – a guide
Discover how to improve the customer experience from when they first step through your door. Learn more about customer interaction in our guide.
How to build a brand identity
Take your brand to new heights and learn how to craft your unique brand identity. Find out how to get started in this Hiscox guide.
How to market a small local business
Read our guide to understand different marketing techniques and ways to engage the community, to increase your local visibility and help your business compete in a crowded market.