
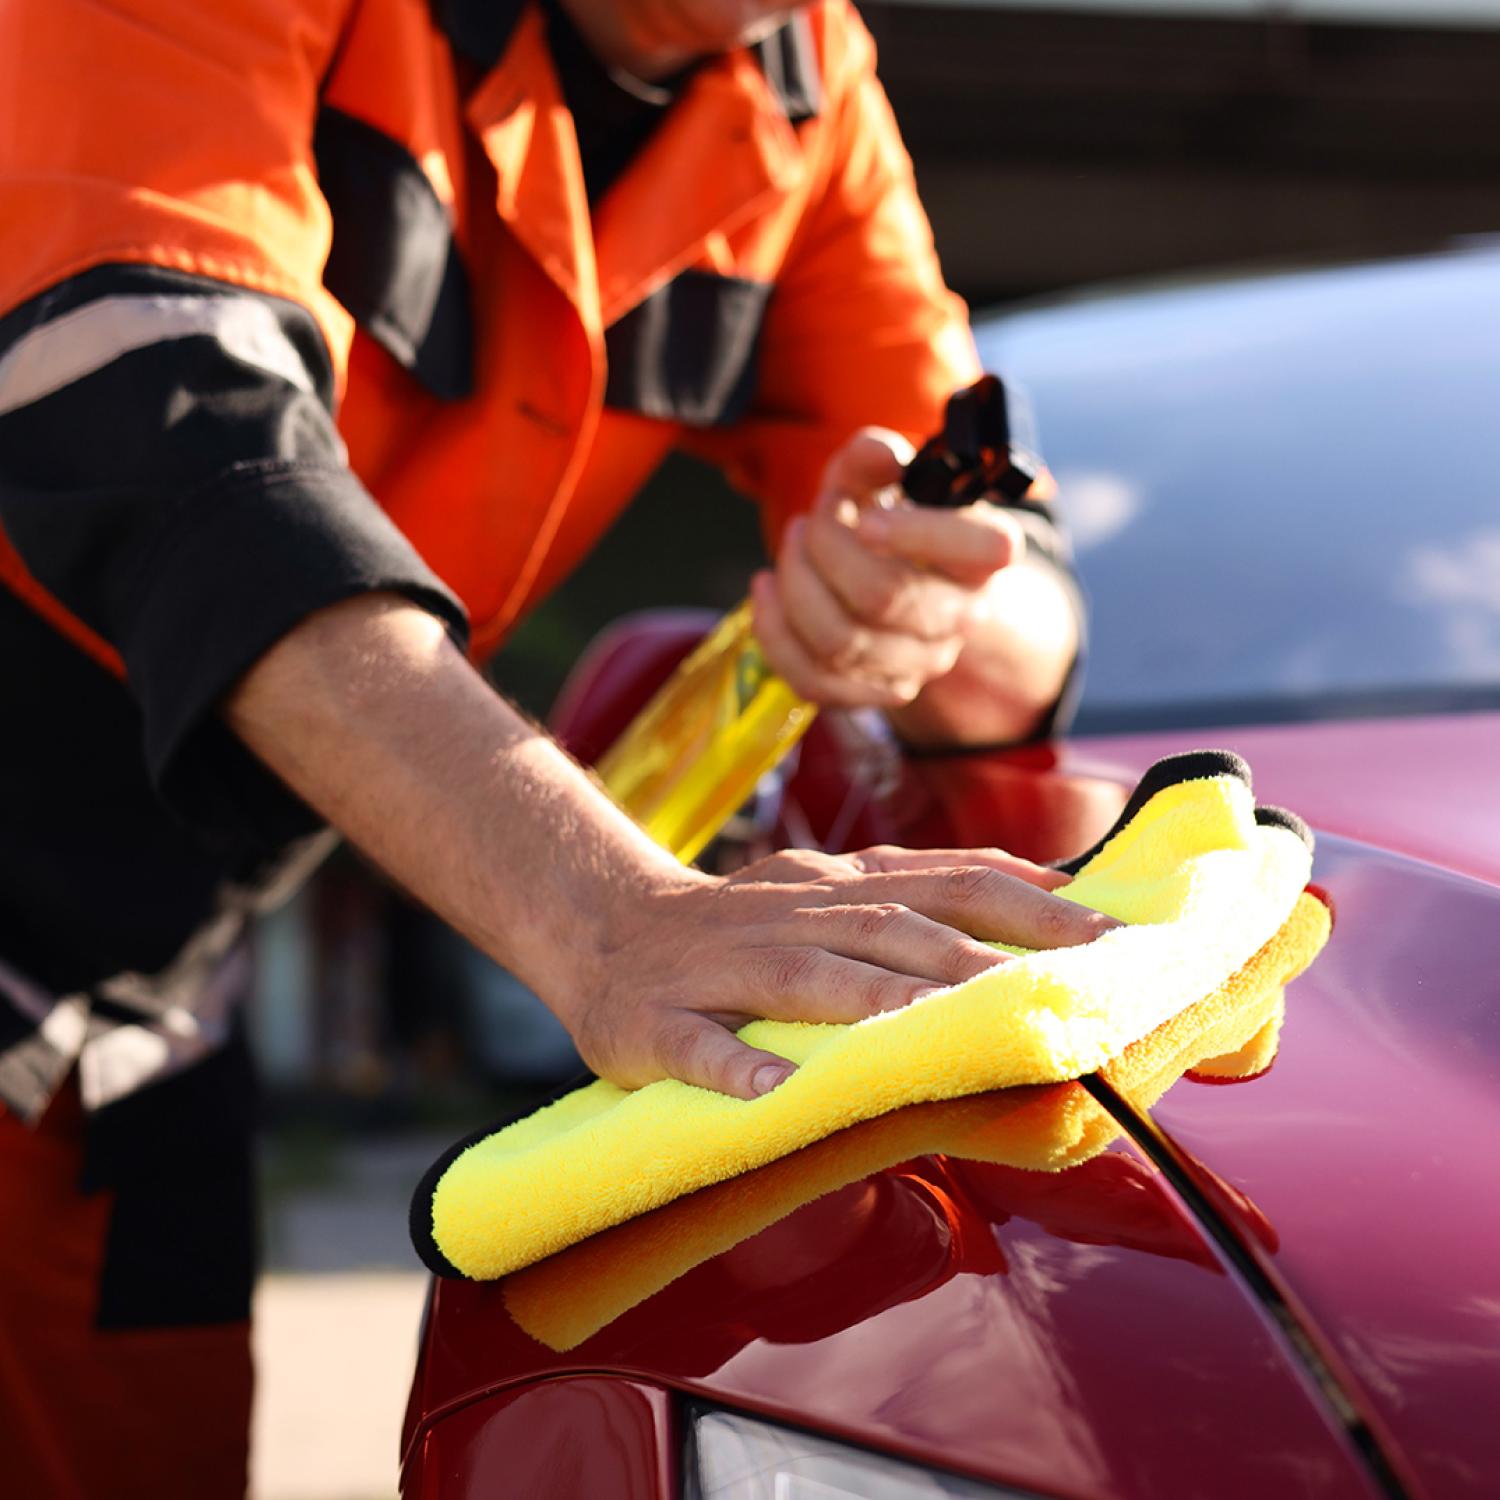


Why do car valeters need insurance?
Car valeters work closely with customers’ vehicles and use specialist equipment in environments where there is a risk of potentially costly or hazardous incidents. Insurance can help manage the financial impact of accidents, injuries, and unexpected damage.
A customer's car is accidentally damaged
Even the most experienced valeter can have an off day. An accidental scratch during polishing, a dent from a misplaced trolley, or damage to interior trim during a deep clean may prompt customers to seek compensation if they feel your work has harmed their vehicle.
Public and products liability insurance can help cover legal defence costs and any compensation owed if a customer makes a claim connected to damage caused by your work.
An employee gets injured on the job
Valeting can involve physical, repetitive work, such as lifting equipment, bending into wheel arches, and handling strong cleaning chemicals. Despite best efforts to keep the workplace safe, injuries can still happen. A staff member might strain their back while lifting a pressure washer, slip on a wet floor, or experience a skin reaction to cleaning products.
Employers' liability insurance can help with the legal costs and compensation payments associated with work-related employee injury or illness claims.
A fire breaks out
Valeting products, such as solvents, polish, and compressed air, can be flammable. A fire, whether caused by a chemical incident or an electrical fault, could damage your equipment, stock, and premises.
Business contents insurance can help cover the cost of repairing or replacing equipment and stock damaged in a fire, reducing the financial impact on your business.
What insurance is available for car valeters?
Public and products liability insurance
Public and products liability insurance can help protect your business if a customer or member of the public is injured or their property is damaged as a result of your work. For car valeters, this might include a customer claiming damage was caused to their vehicle during the valeting process, or a visitor tripping over equipment on your forecourt.
This cover can support legal defence costs and any compensation owed, whether you operate from a fixed location or work on-site at customers' homes and businesses. Cover is available up to £10 million.
Employers' liability insurance
If you employ staff, whether full-time, part-time, or on a casual basis, employers’ liability insurance is legally required in the UK (external link) as soon as you become an employer – unless you employ a family member or someone based outside of England, Scotland and Wales. It can help with the costs of defending or settling a claim if an employee suffers a work-related injury or illness.
For valeting businesses, where physical demands are high and exposure to chemicals is common, this cover provides important protection. At Hiscox, employers' liability is available alongside public liability insurance.
Business contents insurance
The specialist equipment used in car valeting, such as pressure washers, polishing machines, steam cleaners, and wet-dry vacuums, can be expensive. Business contents insurance can help cover the cost of repairing or replacing equipment and stock at your premises if they’re damaged, destroyed, or stolen.
You can also add portable equipment cover (known as property away and in transit insurance) to protect tools and equipment when you're working off-site. Cover can be arranged on a UK-wide basis or even extended to Europe or worldwide, if you work overseas.
Tell us more about your car valeting business and we’ll help to build your tailored insurance policy.
Build my coverInsurance for car valeters: FAQs
Can mobile car valeting businesses get cover?
Yes. Public and products liability insurance can apply whether you operate from a fixed premises or travel to customers. If you work across multiple locations, portable equipment cover can also help protect your tools and equipment while you're on the move, covering accidental loss, damage, or theft away from a fixed base.
Can I get cover for specialist equipment?
From pressure washers and polishing machines to steam cleaners and wet vacuums, business contents insurance can cover the specialist equipment you keep at your premises. For high-value or portable items you regularly use off-site, portable equipment cover could provide protection based on the geographical limits you select.
Am I covered if I store customer vehicles overnight?
Standard public liability insurance covers damage caused by your work, but it may not automatically extend to cover vehicles left in your care overnight. If you regularly store customers' vehicles on your premises, it's worth discussing this with us when setting up your policy to ensure you have the right level of protection. If you need cover for driving or moving customers’ vehicles, you’re likely to need a more specialist motor traders’ insurance policy.
Can I cover transporting equipment between jobs?
You can add portable equipment cover to your business contents insurance policy for equipment that is temporarily away from your premises, including while in transit. This can help protect against accidental loss, damage, or theft while you're travelling between locations.
Am I covered if I subcontract work to other valeters?
If you bring in subcontractors to help with jobs, it's important to check how this affects your policy. Public and products liability insurance can cover claims arising from the activities of your subcontractors, but these should be declared when setting up your cover.
It’s likely that any bona fide subcontractors will be required to hold their own insurance to the same level that you hold. Speak to us when arranging your policy so we can make sure the right protection is in place.
Related articles and guides
How to start a cleaning business
Starting a cleaning business can be an excellent opportunity for entrepreneurs looking to enter a market with consistent demand and relatively low barriers to entry.
Why choose Hiscox Business Insurance?
Our aim is to provide the best business insurance in the market and superior service. We are experts in our field and tailor our products to your business needs.
What business insurance does a sole trader need?
Being your own boss brings freedom, but it could mean you need to consider the insurance asks in your contracts. Read more with our sole trader insurance needs FAQ.